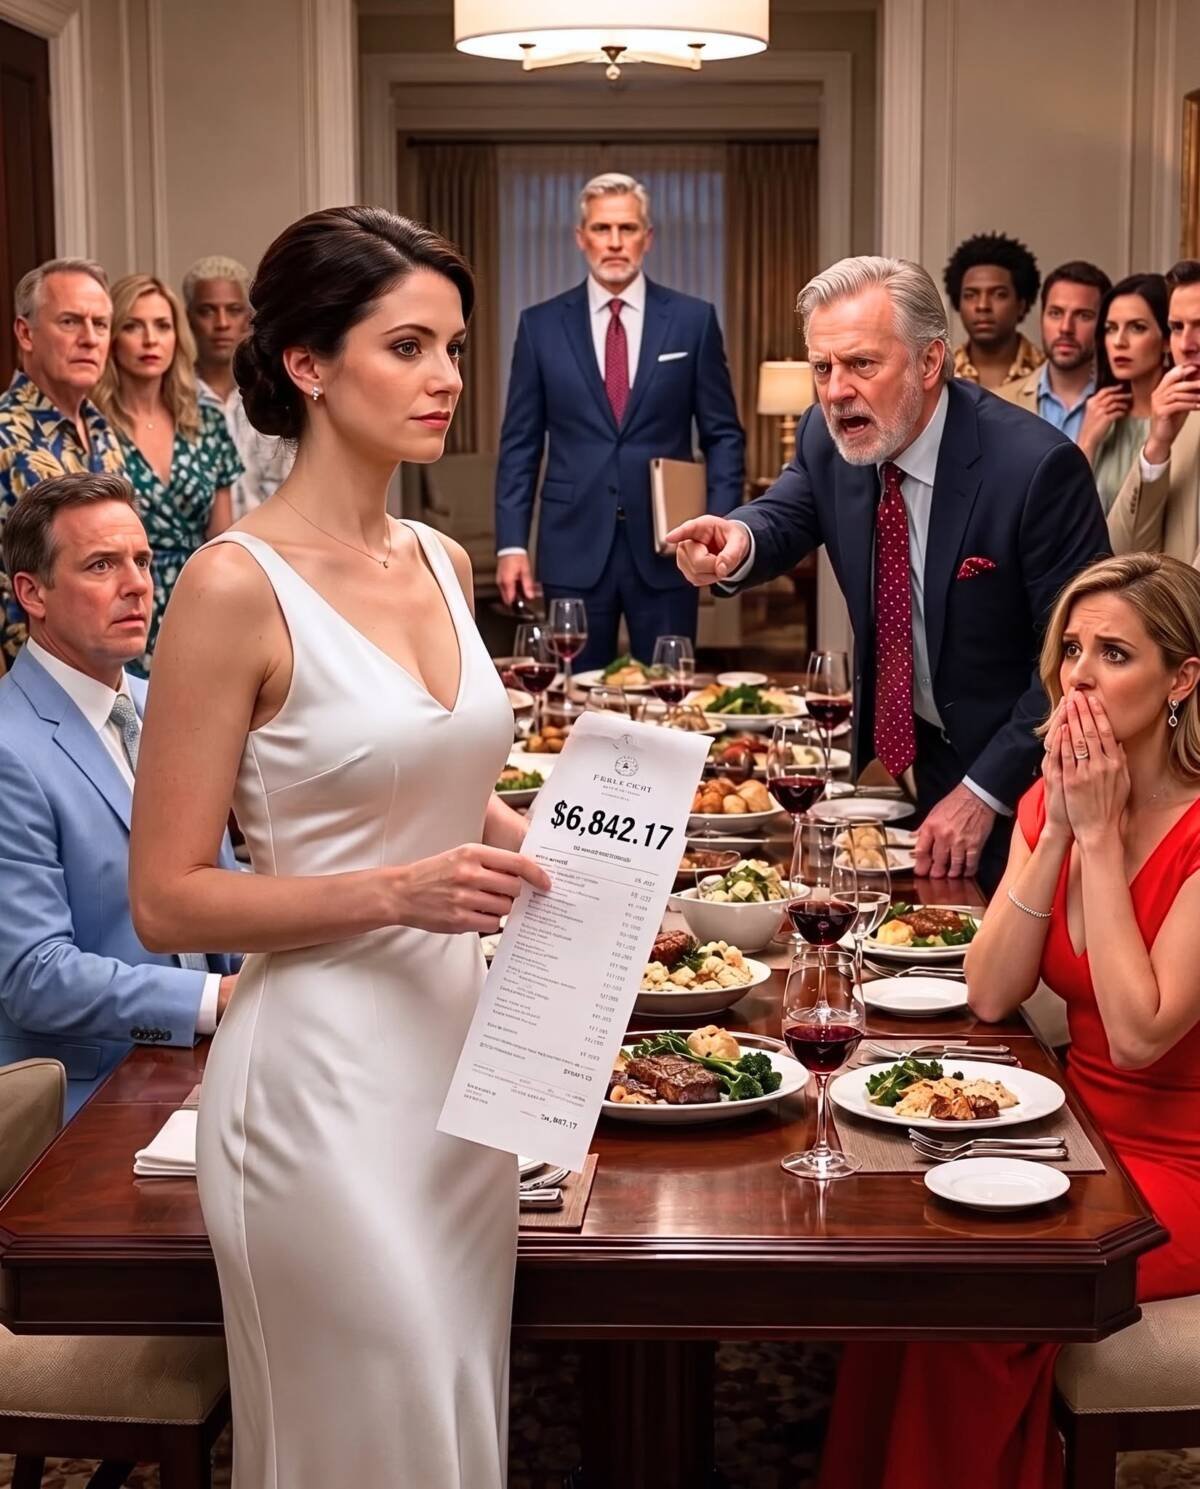
A birthday dinner, a threatening gesture, and a phone call from a bank exposed a family secret that changed everything. What began as an argument over leftovers soon revealed unauthorized financial dealings, a missing $6,500, and a husband who believed his wife’s consent was negotiable.
Introduction: The Birthday Dinner That Exposed a Bigger Problem
I thought I was paying for a birthday dinner.
I had no idea I was about to discover how little my husband’s family respected my boundaries.
My mother-in-law was packing up most of the food I had paid for when I asked her to leave some behind for my daughter. Instead of listening, she accused me of being selfish. My husband sat quietly nearby, his sister watched with amusement, and the atmosphere at the table grew increasingly uncomfortable.
Then my mother-in-law raised her hand toward me.
My eight-year-old daughter froze.
I did not scream. I did not argue any further. I took the remaining food and cake, threw them away, picked up my daughter’s coat, and walked out of the restaurant.
My husband followed me with angry questions. His mother called me dramatic. His sister accused me of ruining the evening.
I left without another word.
At the time, I thought the argument was the worst thing that had happened that night.
The following morning, at 8:17 a.m., a loan officer from First Federal Bank called me with a question that made my stomach drop.
Was I still willing to guarantee a $48,000 business loan for my sister-in-law?
I had never agreed to guarantee anything.
But the bank had my income information, my address, and part of my Social Security number.
Suddenly, the birthday dinner made sense in a way I had not expected. The food was only the beginning. The real problem was that my husband and his family had apparently decided that my money, my financial information, and my future were theirs to use.
What followed forced me to reconsider my marriage, protect my finances, and make a decision that would change my daughter’s life as well as my own.
Part 1: The Birthday Dinner That Changed Everything
By the time dessert arrived, I already regretted inviting my husband’s family to my daughter Lily’s birthday dinner.
I had reserved a private room at a steakhouse in Columbus, Ohio. I paid the deposit, ordered the birthday cake, arranged the dinner, and covered the entire bill.
The total eventually came to $612.47.
Daniel, my husband, had been unemployed for two months, so I had not expected him to contribute much financially. That was not the issue. I was accustomed to handling expenses when necessary, and I did not believe every family gathering needed to be divided down the middle.
What bothered me was the growing assumption that anything I paid for automatically became available to everyone else.
My mother-in-law, Carol, had a habit of treating generosity as an obligation. If I bought groceries, she felt entitled to take some home. If I prepared a meal, she assumed there would be enough for her to pack up whatever she wanted. If I offered to pay for an outing, she rarely considered whether I might have other plans for the things I purchased.
I had overlooked those habits for years because I wanted a peaceful relationship with Daniel’s family.
That evening, however, Carol seemed particularly determined to take control of the situation.
The server had barely finished clearing the plates when she began filling takeout containers with untouched dinner rolls, sliced steak, roasted vegetables, and portions of the remaining cake.
She worked quickly, folding lids and stacking containers as though the food had already been assigned to her.
I watched for a moment, assuming she would leave enough for the rest of us.
Then I realized she was packing nearly everything.
“Leave some for us,” I said. “Lily wanted cake tomorrow.”
Carol continued filling the containers.
“You have plenty of food at home,” she replied.
I tried to keep my voice calm.
“I paid for this dinner.”
That finally made her look up.
“So now you’re keeping score?”
I stared at her, surprised by the accusation.
I had paid for the meal because I wanted Lily to have a special birthday. I had not expected praise, repayment, or even a thank-you. I simply wanted to keep a few pieces of cake for my daughter.
“I’m not keeping score,” I said. “I’m asking you to leave some food here.”
Carol shook her head as though I had made an unreasonable demand.
Across the table, Daniel remained focused on his phone. His sister, Megan, watched the exchange with an expression that suggested she found it entertaining.
I waited for Daniel to say something.
He did not.
When I reached toward the cake box, Carol planted one hand firmly on the table and raised the other toward me.
“Don’t you dare embarrass me in front of my family.”
The room went quiet.
I could hear the faint noise of dishes and conversations from the restaurant outside our private room, but nobody at our table said a word.
Lily sat beside me, completely still.
I saw the expression on her face and understood that the argument had become something much bigger than a disagreement over leftovers.
Carol had raised her hand toward me in anger, and my daughter had witnessed it.
For years, I had tried to keep the peace with Daniel’s family. I had ignored dismissive comments, tolerated uncomfortable exchanges, and convinced myself that avoiding conflict was the mature thing to do.
But I could no longer pretend that keeping everyone comfortable was more important than what my daughter was watching.
I took the box from Carol, walked to the nearby service station, and emptied the remaining cake and food into the trash.
Several people gasped.
I knew the gesture was impulsive. I also knew it would give Carol something new to criticize.
But I was done negotiating over something I had purchased while being treated as though I had no right to decide what happened to it.
“There,” I said. “Now nobody takes it.”
Daniel finally put down his phone and stood up.
“Rachel, what the hell is wrong with you?”
I picked up Lily’s coat.
“What’s wrong is that your mother just made a threatening gesture toward me, and you sat there watching.”
Carol immediately accused me of being dramatic. Megan called me selfish. Daniel demanded that I sit back down and stop making a scene.
I looked at the three of them and realized that none of them was asking whether I was okay.
They were concerned about the embarrassment, the argument, and the fact that I had refused to go along with Carol’s demands.
Nobody seemed concerned about Lily.
I helped my daughter put on her coat, took her hand, and walked out.
I did not wait for Daniel to follow me.
I did not respond to Carol’s accusations.
I did not try to explain myself to Megan.
I drove Lily home, packed two overnight bags, and took her to stay with my friend Jenna.
I needed distance from the argument, and I wanted my daughter somewhere she could relax without watching adults turn every disagreement into a battle.
By the time we arrived, I believed I had already experienced the worst part of the evening.
I was wrong.
Part 2: The Phone Call That Changed Everything
At 8:17 the following morning, Lily was eating cereal at Jenna’s kitchen counter when my phone rang.
The caller introduced himself as a loan officer from First Federal Bank.
He explained that he was contacting me about a $48,000 small-business loan application submitted by my sister-in-law, Megan. The bank needed to confirm whether I was still willing to act as a personal guarantor.
For several seconds, I could not respond.
“I never agreed to guarantee anything,” I finally said.
The loan officer paused.
“Ma’am, your name, income information, and partial Social Security number were submitted with the application yesterday.”
Yesterday.
The word seemed to echo in my head.
While I had been paying for Lily’s birthday dinner, someone had submitted my personal financial information to support a loan for a business I had nothing to do with.
I asked the loan officer to freeze the application and provide copies of whatever records the bank was legally permitted to release.
He explained the next steps and assured me that the bank would document my objection.
When the call ended, I sat quietly for a moment, trying to understand how my information had ended up on the application.
Then I remembered something Daniel had asked me to do three nights earlier.
He had messaged me, saying our apartment complex needed updated income documentation. He asked me to send him a photograph of my latest pay stub.
I had done it without hesitation.
Daniel was my husband. We shared a home, raised a child together, and had been married long enough that requests like that rarely seemed suspicious.
Now I wondered whether the explanation had been deliberately misleading.
I immediately called Daniel.
He answered on the second ring.
“Where are you?”
I ignored the question.
“Did you put my information on Megan’s loan application?”
Silence.
It was not the silence of someone who had no idea what I was talking about. It was the silence of someone deciding how to respond.
Finally, Daniel exhaled.
“It wasn’t supposed to be a big deal.”
I walked into Jenna’s laundry room and closed the door so Lily would not hear the conversation.
“You used my pay stub.”
“I gave Megan the numbers. The bank still has to approve everything.”
“That is not an answer.”
Daniel began explaining that Megan needed financing to open a salon. Carol had already contributed $15,000, Megan’s credit was not strong enough to qualify for the loan on her own, and Daniel was unemployed.
According to him, I was the only person in the family with a reliable income.
I laughed, although nothing about the situation was funny.
“So you volunteered me.”
“We’re married, Rachel.”
“That does not make my signature yours.”
Daniel insisted that nobody had forged my signature. He argued that the bank was only calling to confirm the application and that I could approve it if I wanted to.
He made it sound as though the only remaining obstacle was my willingness to cooperate.
Then he said something that made the situation even more disturbing.
“After what you pulled last night, you owe my family some goodwill.”
I ended the call.
I had called him to ask why my financial information was being used without my permission. Instead of addressing the question, he had tried to make me feel guilty for refusing to help his sister.
The birthday dinner suddenly looked different.
Carol’s insistence on taking the leftovers, Daniel’s silence, and the family’s expectation that I should accommodate everyone had all been part of the same broader problem.
They expected me to give without asking questions.
And when I resisted, they treated me as though I were the one causing trouble.
Part 3: The Loan Application Was Only the Beginning
Within an hour, First Federal emailed the documents it was legally permitted to provide.
The application listed my employer, salary, home address, and the last four digits of my Social Security number.
The signature line was blank.
That detail mattered. I could not conclude from the paperwork alone that anyone had forged my signature, but I could see that my information had been used in an application I had never authorized.
I showed the documents to Jenna.
She read them twice before looking up.
“You need to freeze your credit.”
I agreed.
I contacted the three major U.S. credit bureaus and placed security freezes on my credit files. I changed the passwords on my banking and payroll accounts, enabled additional security measures, and contacted my employer’s human resources department to ask how my employment and income information could be protected.
I also began keeping a detailed record of every call, email, and message connected to the application.
I wanted a clear timeline of what had happened and evidence of what I had and had not authorized.
Then I checked our joint bank account.
That was when I discovered another problem.
Four days earlier, Daniel had transferred $6,500 from our joint savings account into his personal account.
The transaction memo read “family investment.”
Most of that money had come from my paychecks over the previous year. I had been setting it aside for Lily’s summer care, emergencies, and a future apartment deposit.
I stared at the transaction for several seconds, hoping I had misunderstood what I was seeing.
I had not.
I called Daniel again.
“Did you send Megan $6,500?”
He sounded irritated.
“Mom said she was short.”
“You didn’t ask me.”
“I knew what you’d say.”
That sentence was more revealing than any explanation he could have offered.
“You knew I would say no, so you took it anyway.”
“It’s our money.”
“Then why did you move it into your private account first?”
He had no convincing answer.
Daniel insisted he had been trying to help his sister. He said the money was an investment in Megan’s future and suggested that I was overreacting because I was already angry about the birthday dinner.
But the problem was not whether Megan deserved help.
The problem was that Daniel had moved a substantial amount of money without discussing it with me, then used my expected refusal as an excuse for doing so.
I had believed we were making financial decisions together.
He had apparently believed that if he thought his decision was reasonable, he did not need my agreement.
By noon, Carol had started texting me.
She accused me of embarrassing her, claimed I was trying to destroy Megan’s future, and insisted Daniel had every right to use marital money to help his sister.
Then she sent a message that made me stop reading and take a screenshot.
“If you call the bank again and cause trouble, don’t expect this family to forgive you.”
I saved the message with the other records.
Carol was not asking me to clarify a misunderstanding. She was pressuring me to stop questioning a financial application that involved my personal information.
I had no intention of doing that.
That afternoon, I met with a family-law attorney named Melissa Grant.
I explained the birthday dinner, the loan application, the transfer from our joint savings, and the messages I had received from Daniel and Carol.
I told Melissa that I was not yet certain whether I wanted a divorce. I needed to understand my legal position before making decisions about my marriage.
She listened carefully and asked whether I knew if Daniel had opened any other accounts or applied for additional credit using my information.
I did not.
We reviewed my credit reports.
There were no new accounts, but there were two recent hard inquiries.
One came from First Federal.
The other came from an online lender Daniel had never mentioned.
The date of the second inquiry made my stomach tighten.
It fell during the same week Daniel had told me he was looking into refinancing options for our car.
I did not yet know what the second inquiry meant, but I knew I needed an explanation.
Melissa advised me to preserve all the records, avoid making accusations I could not substantiate, and take practical steps to protect my finances.
That evening, I opened a separate checking account and redirected my paycheck there. I left enough money in the joint account to cover rent, utilities, and Lily’s immediate expenses, and I continued documenting every transaction.
I did not want to make a decision in anger that could complicate matters later.
I wanted to protect myself and my daughter while giving the facts time to become clear.
Then Megan left me a voicemail.
She was crying.
“First Federal suspended my loan application. I already signed a lease. You ruined this for me.”
It was the first time anyone had mentioned a lease.
Suddenly, the urgency surrounding the loan made more sense.
Megan had committed to a three-year commercial lease for a salon suite. She had spent Carol’s money on the deposit and ordered equipment before securing the financing she needed to open the business.
The $48,000 loan was intended to cover renovations, equipment, insurance, inventory, and several months of operating expenses.
She had committed herself financially before obtaining the money to carry out the plan.
Now she was angry because the bank would not proceed without resolving the guarantor issue.
I understood that Megan was facing a serious problem. She might lose money, disappoint people, and have to reconsider a business she had already begun planning.
But those consequences did not make me responsible for guaranteeing a debt I had never agreed to carry.
I had not signed a contract.
I had not authorized the application.
And I had not promised to finance her business.
Part 4: My Husband Expected Me to Say Yes Eventually
Melissa advised me to keep all communication about the loan in writing.
She also warned me not to empty our joint account or move money secretly. Protecting myself did not mean giving Daniel grounds to claim that I had mishandled marital funds.
I followed her advice and sent him an email.
I stated clearly that I had never authorized him, Megan, or Carol to use my personal or financial information for any loan. I also requested the return of the $6,500 transferred from our savings.
Daniel responded twenty-three minutes later.
He did not deny making the transfer.
Instead, he wrote that he had only been trying to help Megan and reminded me that marriage meant supporting each other’s families.
I read his response twice.
It was remarkable how carefully he avoided addressing the actual problem.
I replied with one sentence:
“Supporting your family does not mean giving them access to me without my consent.”
That evening, Daniel arrived at Jenna’s house.
I saw him standing on the porch in the same gray jacket he had worn to Lily’s birthday dinner. Jenna asked whether I wanted her to send him away.
“No,” I said. “But stay nearby.”
I stepped outside and closed the door behind me.
Daniel immediately began explaining Megan’s situation. She could lose the lease, Carol might lose the $15,000 she had invested, and Megan would be humiliated because she had already told people that the salon was opening.
I listened until he finished.
Then I asked the question he had avoided.
“When were you planning to tell me about the $6,500?”
He rubbed his forehead.
“I was going to put it back.”
“With what money?”
“I’m interviewing.”
“An interview isn’t money.”
He looked away.
I asked about the second lender.
His expression changed before he said anything.
Daniel finally admitted that he had started another application using my income because he wanted to see how much financing we might qualify for. He insisted he had never completed the final submission and repeated that he had not signed my name.
“You used my information twice?”
“I didn’t sign your name.”
“You keep saying that as though it makes this normal.”
“I was trying to fix things.”
“For Megan?”
“For all of us.”
I stared at him.
“How does putting $48,000 of her business debt on me help Lily or me?”
He had no answer.
Then he said the sentence that explained more than all his previous excuses.
“Mom said you’d say no if we asked first.”
There it was.
They had anticipated my refusal and decided to move forward anyway.
This was not simply a misunderstanding or a rushed application. Daniel had believed that because he knew I would object, he should try to arrange the financing before I could stop it.
He had treated my refusal as a problem to work around rather than a decision to respect.
I opened the door.
“You need to leave.”
“Rachel, come on.”
“You need to leave.”
Daniel stepped closer and lowered his voice, adopting the calm, private tone he often used when he wanted me to reconsider my position.
“We can solve this. Tell the bank you’re willing to reconsider. Megan can refinance you off the loan later.”
“No.”
“You don’t even know her business plan.”
“No.”
“Can you stop saying no for five seconds?”
“No.”
Jenna opened the door behind me.
Daniel looked at her, then back at me. He finally understood that the conversation was over.
He left without saying anything else.
The following morning, First Federal’s fraud and compliance department called to confirm that the application had been closed.
Later that day, Megan emailed me.
She claimed Daniel had told her I was “basically on board” and that the bank’s call was supposed to be a formality.
Then she undermined her own explanation.
In the same email, she acknowledged that Daniel knew I was cautious with money and believed I would be easier to persuade once the application was already in motion.
I forwarded the message to Melissa and saved copies in several places.
I no longer wanted to rely on verbal explanations that could later be denied or reinterpreted.
I wanted a clear record of what had happened.
Carol called from an unfamiliar number because I had already blocked hers.
She accused me of turning her children against each other, ruining Megan’s future, and wasting food at Lily’s birthday dinner out of spite.
I finally understood why she kept returning to the leftovers.
If the argument remained about food, she could portray me as wasteful and unreasonable. She could make the entire story about my behavior at the restaurant.
But the financial questions were much harder to dismiss.
“This is not about leftovers,” I told her.
“It absolutely is. You behaved irrationally.”
“You raised your hand toward me in front of my daughter, and the next morning a bank called because my information was on Megan’s loan application.”
There was a brief silence.
Then Carol gave me the same answer Daniel had repeated throughout the week.
“Families help each other.”
I took a breath.
“That answer tells me everything I need to know.”
I hung up.
For the first time in years, I stopped trying to find a way to make Carol understand my point of view.
She did not need to agree with me for my boundaries to matter.
Part 5: The Money Came Back, but the Trust Did Not
Two days later, the $6,500 was returned to our joint account.
It did not happen because Daniel had suddenly understood why I was angry.
Carol gave him the money after Megan complained that I was “forcing Mom to cover your share.” I discovered that detail when Daniel accidentally forwarded Megan’s message to me instead of sending it to the intended recipient.
I saved that message, too.
Over the following week, Daniel repeated different versions of the same argument.
Megan would repay the loan.
The salon would succeed.
The guarantee was only a precaution.
Married couples were supposed to make sacrifices for family.
None of those explanations addressed the central issue.
I had never agreed to any of it.
When I finally met Daniel at Melissa’s office, he arrived with his own attorney.
Seeing him there made our separation feel real in a way that the previous arguments had not. We were no longer trying to resolve a disagreement at home. We were discussing our finances, our responsibilities, and the future of our family with legal counsel present.
We worked out a regular schedule for Daniel to spend time with Lily and agreed that neither of us would discuss the conflict with her.
I returned to the apartment with Lily while Daniel moved in with Carol until we could determine what came next.....